
torstennaugle0
How To Teach Mortgage Better Than Anyone Else
There is a version of the housing market story that gets told over and over, and it goes like this: prices are high, rates are high, nothing is affordable, and the only people buying are the ones with cash. That version is not wrong, exactly. It is just incomplete.
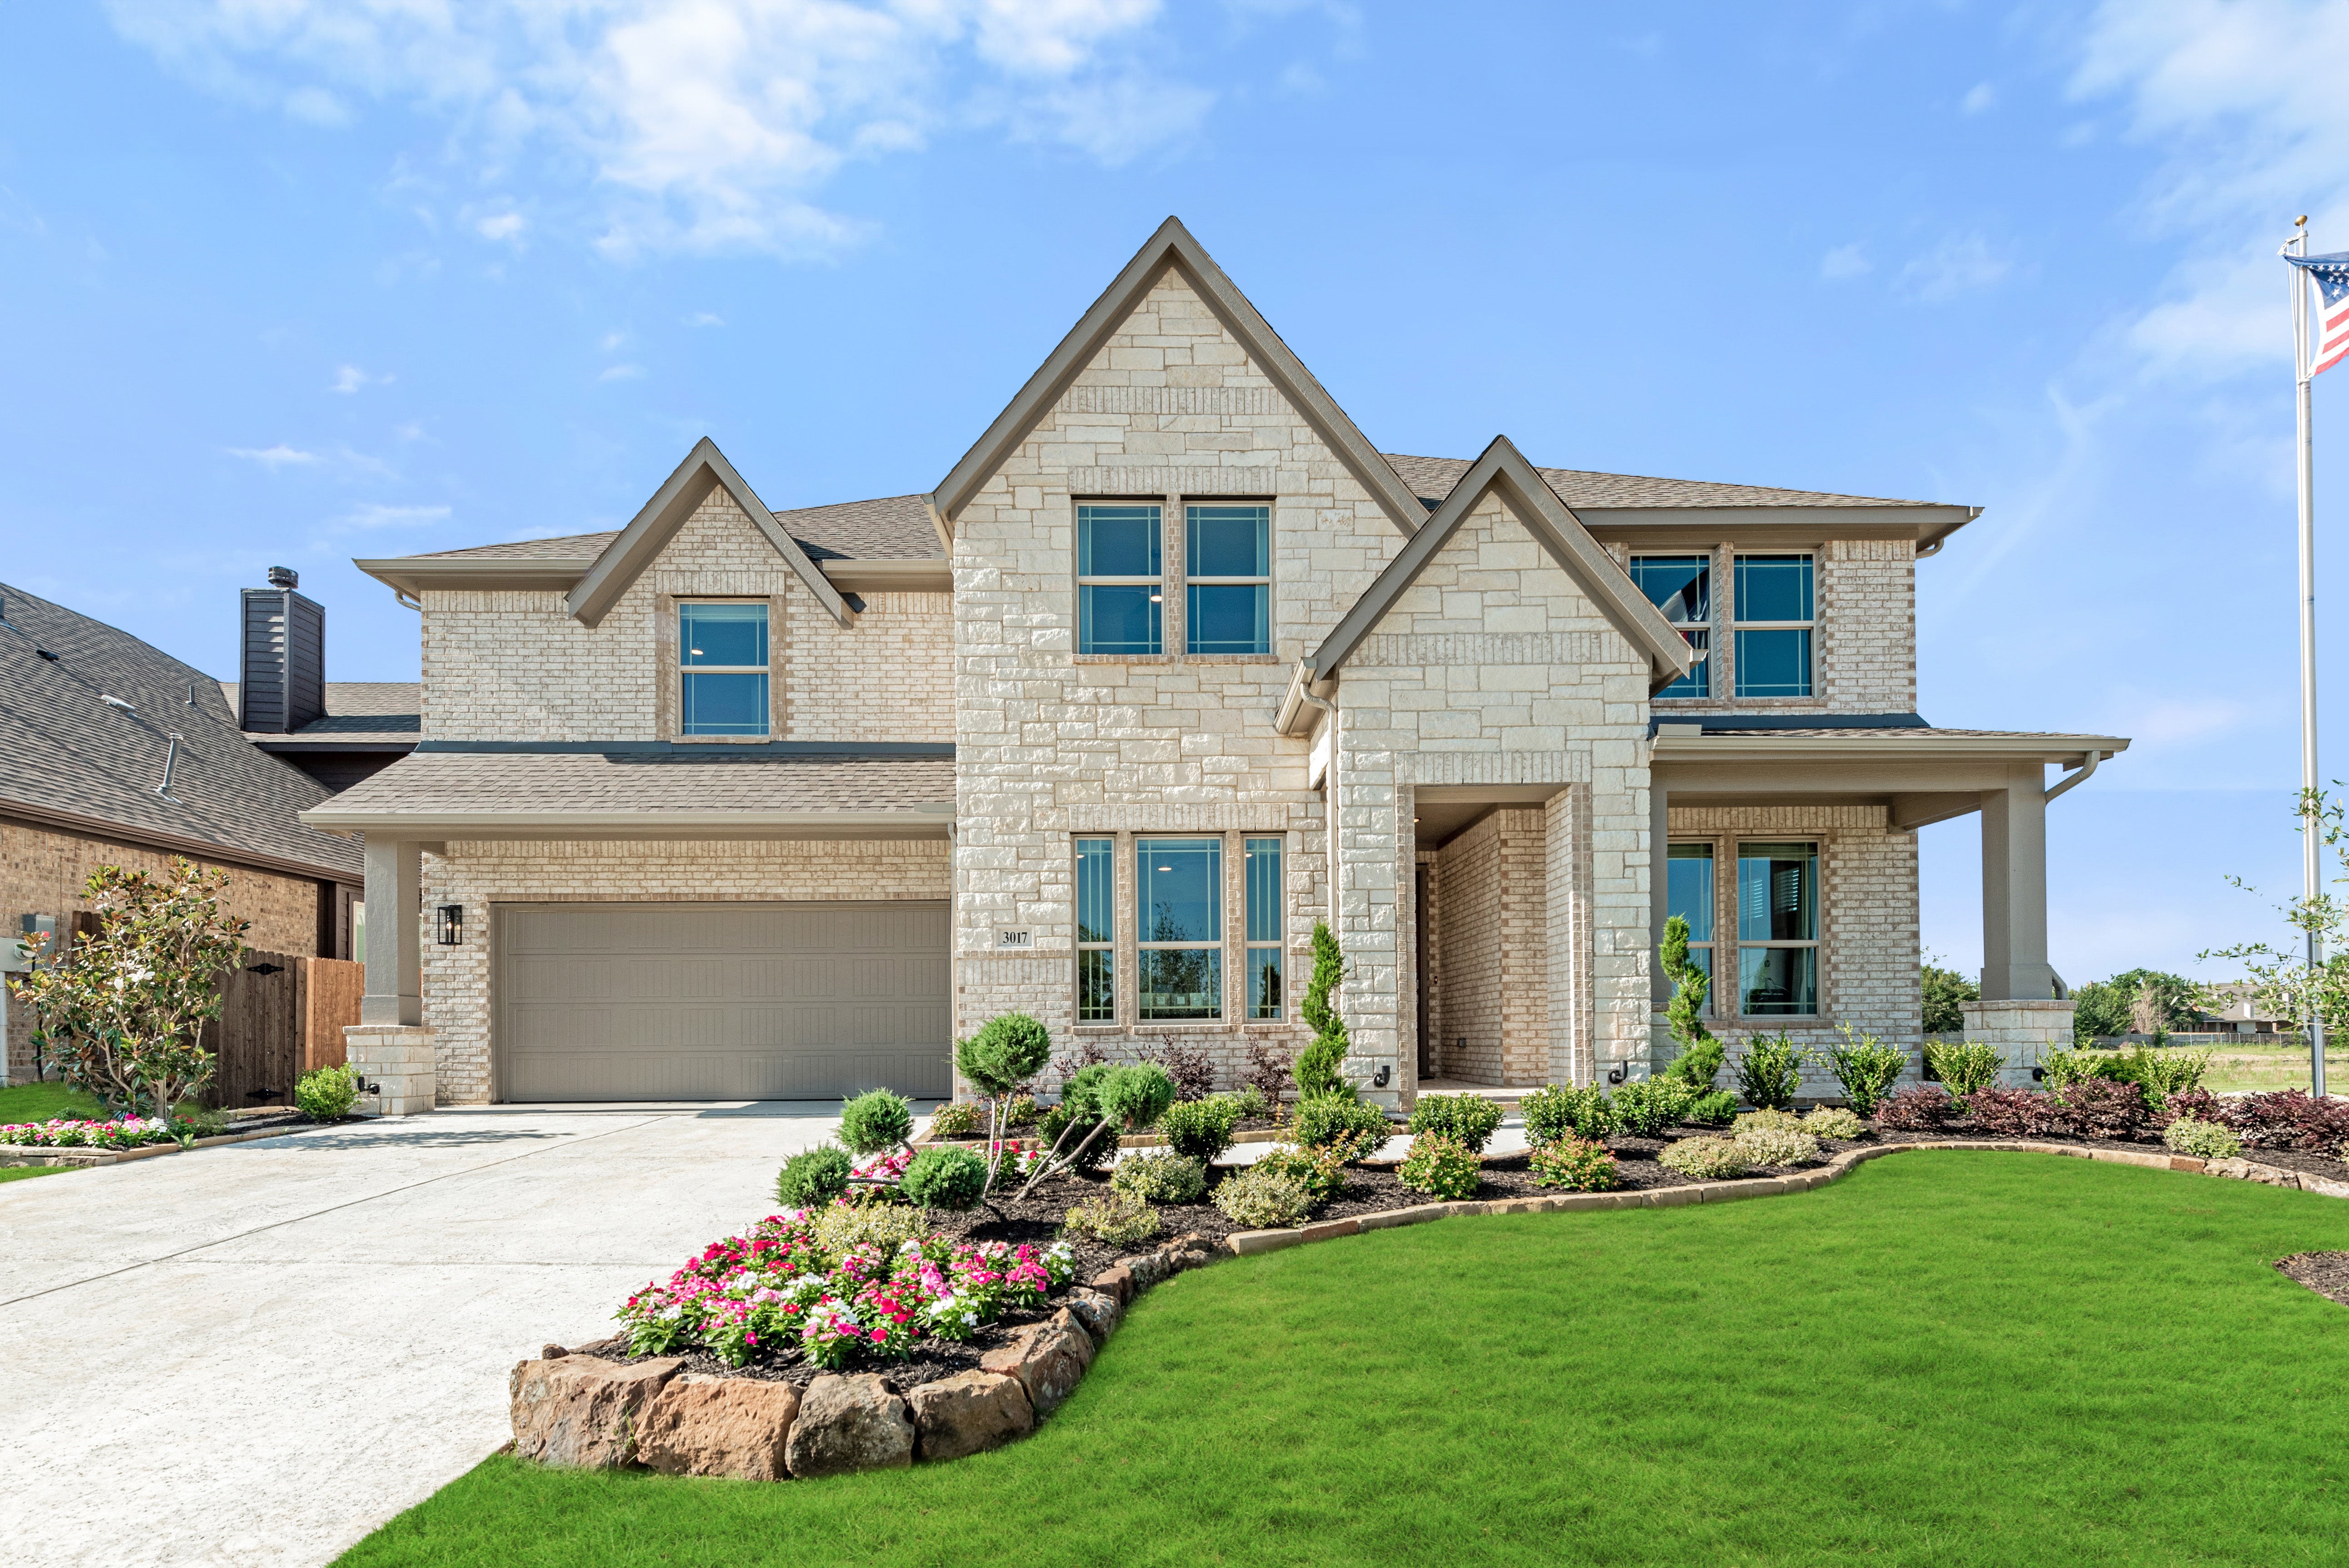 Home prices at the national level have remained well above their pre-pandemic levels even as sales volume collapsed. The reason is supply. Homeowners who locked in three percent mortgages in 2020 and 2021 have almost no incentive to sell, which means the correction that many analysts were expecting simply did not materialize the way the data suggested it should.
 Here is what that creates for someone with solid credit and a real pre-approval in hand: more room to negotiate than the market’s reputation suggests. The panic buyers are gone. The buyers who showed up with letters waiving inspections and offering a hundred thousand over asking have mostly sat back down. What remains is a more functional market, even if it is not a cheap one.
 Shop more than one institution, because the spread in rates and costs is real. A 0.25 percent gap between two lenders’ quotes adds up to real money that most buyers leave on the table by taking the first offer they receive. Lender fees vary too. Do not compare rate quotes without also comparing origination fees, points, and closing costs.
 The appraisal is the lender’s check, not yours. When the appraisal comes in below contract, the deal does not automatically die, but it does require a decision. Ask your agent how common appraisal gaps have been in your target price range and neighborhood.
 Budget between two and five percent depending on your loan type and the state you are buying in. First-time buyers routinely underestimate this number. Ask your lender for a Loan Estimate before you make any offers, so you can plan your cash position accurately.
 The timing question, whether to buy now or wait for rates to come down, is the one that trips up more buyers than any other single factor. The record on market timing for owner-occupied housing is not encouraging. The more useful question is not whether now is the right time in the abstract; it is whether you can carry the payment without strain.
Buyers who take the time to do their homework tend to find that there are still good properties available at realistic prices. Spending twenty minutes with current homes for sale and market analytics is a better use of your time than waiting for conditions that may never arrive.